Promises Delivered?
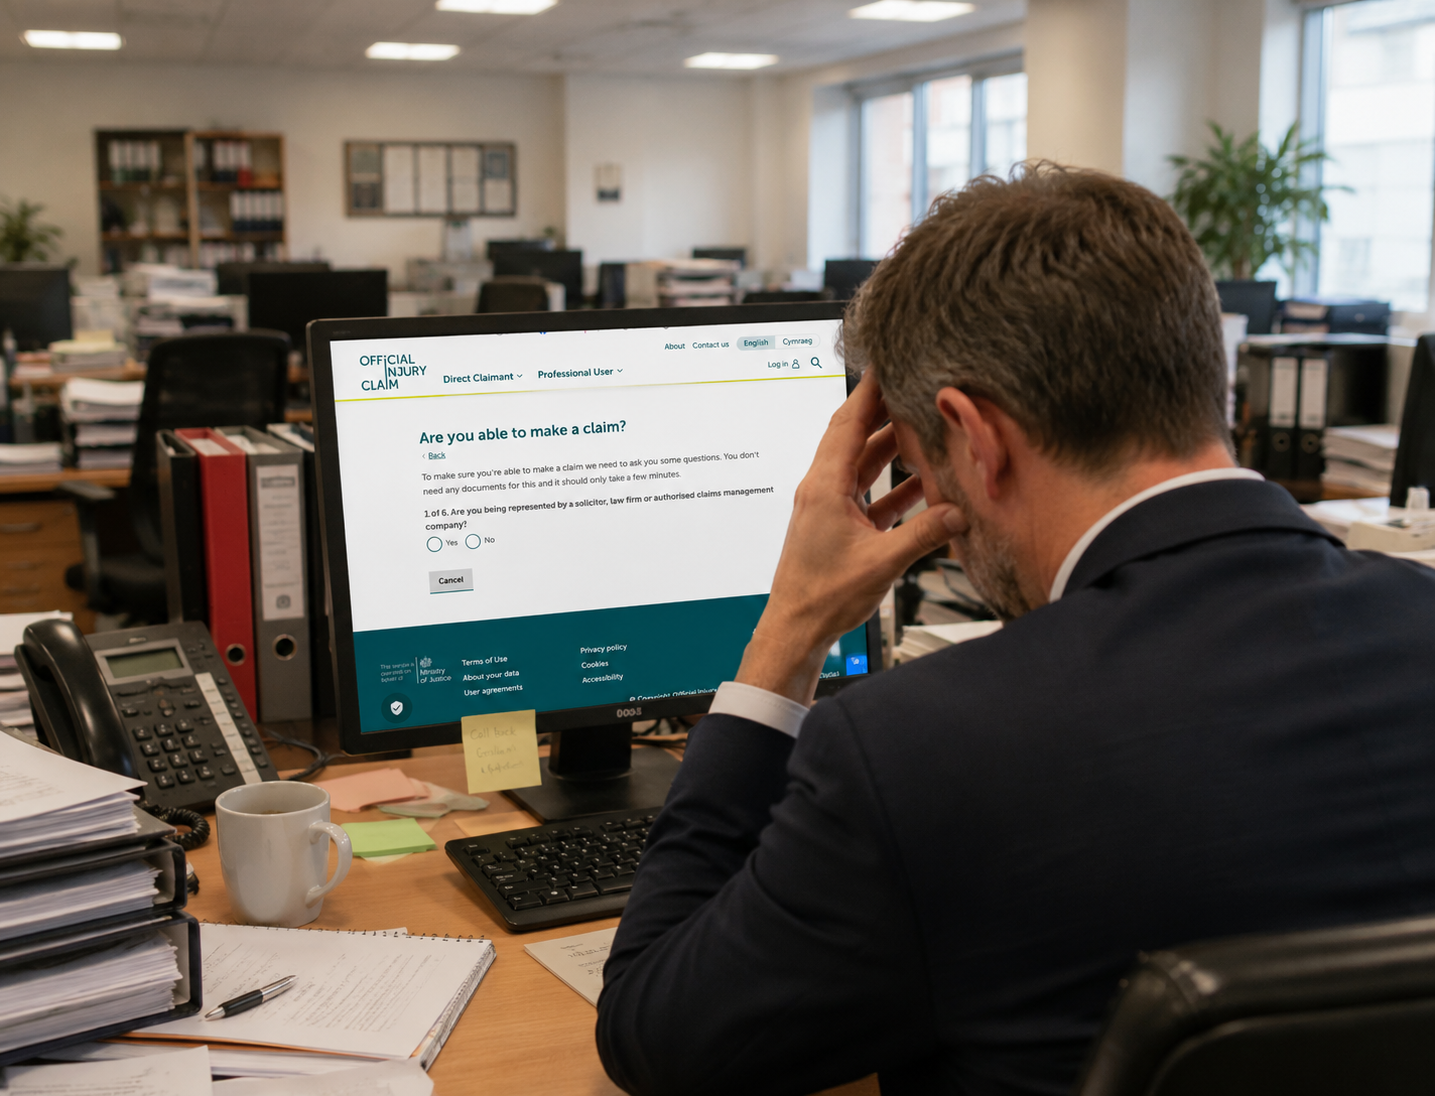
Five years after the introduction of the Official Injury Claim (OIC) portal and the Whiplash Reforms, it is an appropriate moment to assess whether the system has achieved what it set out to do.
The objectives were clear. The Government sought to reduce the cost of low-value road traffic injury claims, encourage claimants to pursue claims without legal representation, reduce insurance fraud, streamline claims handling and ultimately deliver lower motor insurance premiums to consumers.
By one measure, the portal has been active. Since launch in May 2021, more than 1 million claims have been submitted through the OIC platform, with over 336,000 claims settled. However, the headline statistics reveal a system that has largely failed to achieve its core ambitions.
The most obvious failure is claimant self-representation. The OIC was designed around the premise that injured motorists could pursue claims without solicitors. Yet only around 12% of claims are brought by unrepresented claimants, with almost 88% continuing to require professional representation. After five years, this cannot reasonably be described as a successful self-service platform.
Technology
From a technology perspective, there is little evidence that the portal represented a particularly innovative undertaking. The platform appears to be based largely on established enterprise workflow and case-management technology, integrating authentication, document management, claims processing and reporting functions. Whilst complex from a governance perspective, the underlying technical requirements are neither unique nor especially challenging by modern standards.
Indeed, if a private-sector claims technology business were commissioned to build a comparable system today using modern cloud infrastructure, workflow automation and AI-assisted development tools, a functional equivalent could likely be delivered within three to six months. The original programme took several years to reach implementation. Whilst public sector procurement, stakeholder management and regulatory oversight inevitably add complexity, it is difficult to avoid the conclusion that delivery timescales were significantly extended by bureaucracy rather than technical necessity.
The financial cost of the programme remains surprisingly opaque. Although the portal was funded through the Motor Insurers' Bureau rather than directly by taxpayers, no clear public figure appears to exist for either the total development cost or the ongoing operational expenditure. For a programme introduced on the basis of consumer benefit and market reform, this lack of transparency is difficult to justify.
The operational performance of the platform also remains concerning. More than 286,000 claims have exited the portal without settlement since launch. Even amongst settled claims, average resolution times have frequently approached or exceeded a year, undermining the notion of a faster and more efficient digital claims process.
Meanwhile, the broader claims market has contracted dramatically. Motor injury claims have fallen substantially since the reforms were introduced. Supporters point to this as evidence of success. Critics argue that the reduction reflects barriers to access, reduced compensation levels and claimant disengagement rather than the elimination of fraudulent or unmeritorious claims. The available data does not conclusively support either position.
Perhaps the most significant question concerns motor insurance premiums. The central political justification for the reforms was that insurer savings would be passed on to consumers. Five years later, motorists have experienced some of the sharpest premium increases on record. Whilst insurers cite inflation, vehicle repair costs (while ignoring the reduction in accidents thanks to ADAS & other driver aids) and supply chain pressures, the industry has yet to provide compelling evidence that the savings generated by the reforms have been returned to policyholders in any meaningful or measurable way.
Ultimately, the OIC cannot be described as a catastrophic technical failure. It functions, processes claims and has become embedded within the personal injury landscape. However, judged against its original objectives, the outcome is considerably less impressive.
Five years on, the portal has failed to create a genuinely self-service claims environment, failed to demonstrate meaningful consumer savings, failed to provide transparency around programme costs and continues to generate significant operational challenges. It stands as a familiar example of a public-sector digital transformation project that consumed substantial time and resources, delivered a functioning product, but fell materially short of the promises used to justify its creation.