Rerating in Motor Claims: The Critical Role of Independent Engineers
Rerating is often reduced to a simple question: why is more being claimed than was paid? In reality, that framing misses the point. At its core, rerating exists because insurers operate in a different market to claimants.
Retail vs wholesale: the real distinction
The legal position, shaped by Coles v Hetherton, is clear:
the recoverable loss is the reasonable cost of repair in the open market, not the insurer’s discounted cost.
Insurers buy repairs at scale. They negotiate labour rates, parts pricing and process efficiencies. Claimants do not & that difference creates two numbers:
The net cost (what is actually paid), and
The market cost (what is reasonably recoverable)
Rerating is simply the bridge between them.
Why engineers are central, not peripheral
This is where independent engineers come into their own. Their role is not to validate an invoice. It is to define the correct number in the first place.
That requires stepping outside the insurer’s supply chain and asking a different question:
what would this repair reasonably cost in the open market?
To answer that, engineers bring structure and consistency: Thatcham labour times, regional retail labour rates, OEM or pattern parts pricing, full repair methodology, including strip, refit, paint, calibration, zone 99 items etc.
In effect, they convert a repair from a commercial transaction into a defensible measure of loss. Without that step, rerating is just arithmetic. With it, it becomes evidence.
Two estimates, one outcome
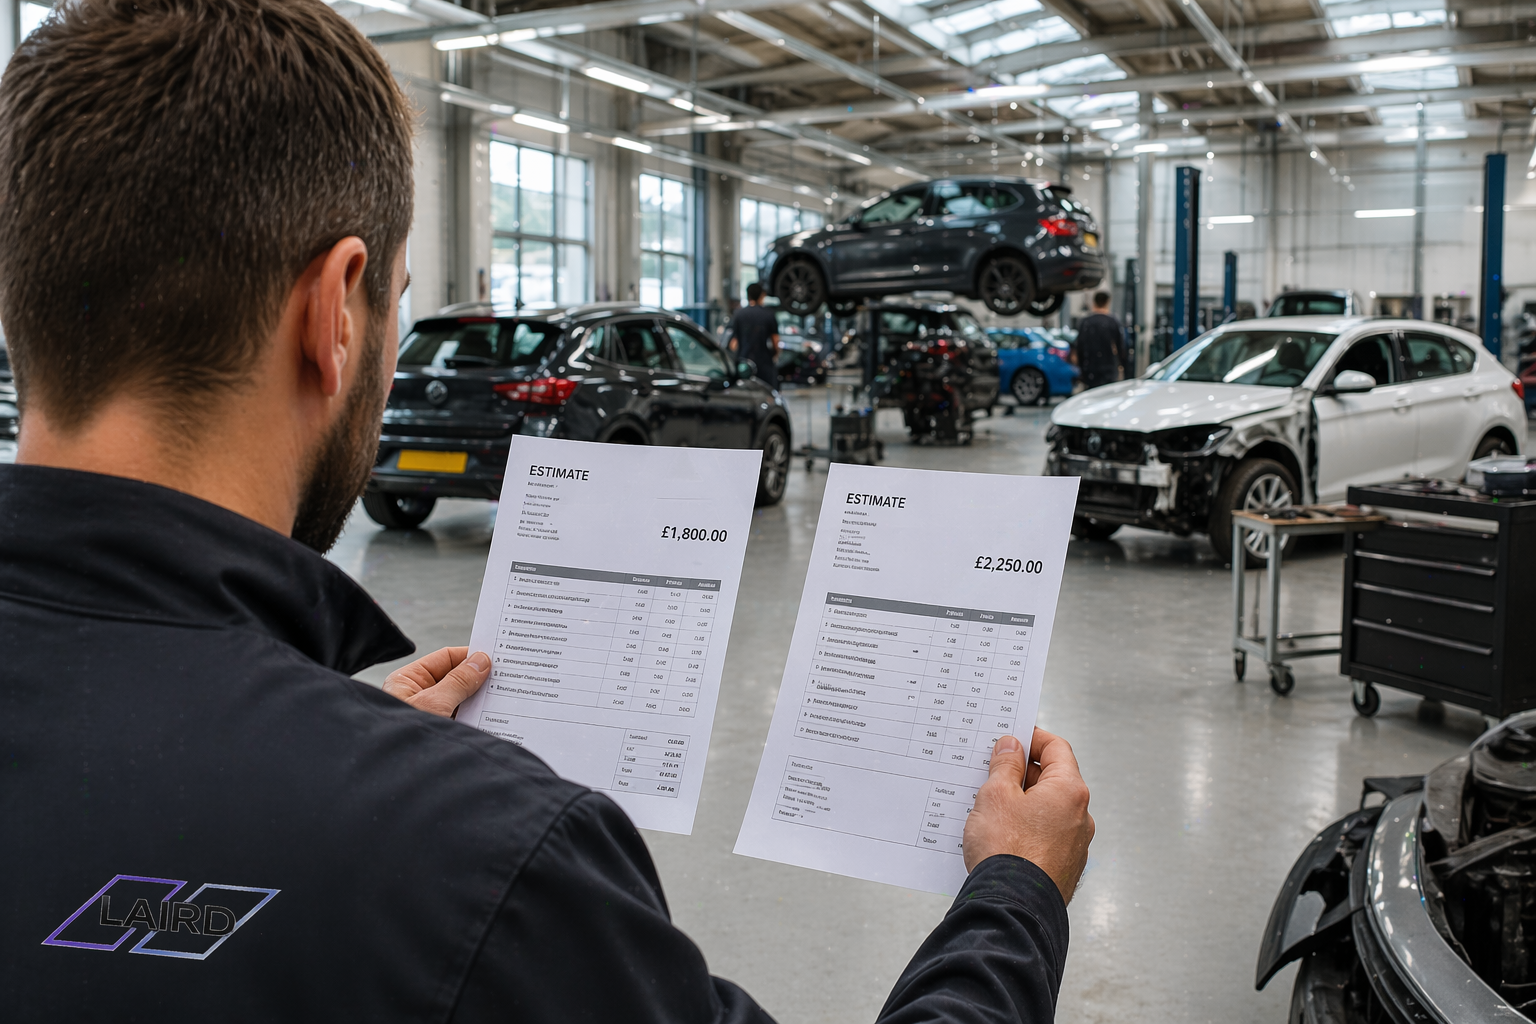
In practice, engineers are often working with two views of the same repair:
1. Operational estimateWhat the repair actually costs within a managed network.
2. Market estimateWhat the same repair would cost a retail customer.
The gap between the two is where rerating sits.
But that gap only holds if the market estimate is credible, consistent and grounded in real-world data.
Where claims succeed, and where they fail
Defendants rarely succeed by arguing:
“you paid less, so we should pay less”
That argument has limited weight. Challenges land when the engineering doesn’t stand up: labour rates that don’t reflect geography, repair times that exceed accepted benchmarks, methodology that cannot be justified
In short, weak engineering undermines strong claims.
Accident management and credit repair: a parallel model
Accident management companies approach the same issue differently, but arrive in a similar place.
Instead of rerating after the event, they structure repairs on a credit basis, establish a retail-facing liability upfront, recover that figure directly
Different route, same test:
is the total cost a reasonable market rate?
Once again, the answer depends on the quality of the supporting evidence, and that usually means engineering input.
ABI, GTA and increasing scrutiny
Industry frameworks like the ABI GTA are pushing towards greater transparency, more consistent repair pathways, clearer alignment on recoverable costs. But they don’t remove the need for judgement. If anything, they increase the expectation that costs are properly evidenced and technically justified.
The Independent Engineer
Rerating is often viewed with suspicion. In practice, it reflects a structural reality; insurers operate at wholesale cost, claimants are entitled to retail indemnity. The law prevents the at-fault party from benefiting from insurer efficiencies.
Independent engineers sit in the middle of that tension. They ensure that what is claimed is not just higher, but correct.
Rerating isn’t really about uplift. It’s about translation, and the accuracy of that translation depends, more than anything else, on the independence, methodology and credibility of the engineer behind it.